What if your child dreamsbigger than you do?

Then you’d better be ready.

QR code. Scan it with your phone camera to open baby.money and install the app.Scan to install on your phone
Get it onApp Store Get it onGoogle Play
Your child’s PAN is not required.

How your money flows

Your bankYou choose the amount
The fund houseInvested directly

Your money is always held with the fund house directly.

baby.money is a platform by Fluential Wealth Technologies, an AMFI Registered Mutual Fund Distributor of SEBI Regulated Entities. ARN-357176

SBI HDFC ICICI Axis
First, what could they become?

Pick a dream. We’ll show you the real road to it, and the plan that gets them there.

Aarav’s road to becoming…

a Doctor

This path could cost about
by the time they’re ready

Stays on your device. We don’t send it anywhere.

How old are they today?1 year
What could you invest each month?₹5,000

What a Doctor really costs, in future rupees

How we calculated this: sources and assumptions
Assumptions: India · full “cost-to-launch” · education inflation 10%/yr (higher-ed runs 10–15%/yr, per 21kSchool, Kotak MF, EduFund 2025) · investment growth 12%/yr assumed as a true annual rate (the monthly rate used is its twelfth root, so a full year compounds to exactly 12%). SIP instalments are treated as invested on their debit date. Costs shown are the amount payable in the year they fall due. The coverage percentage compares your fund’s value at 18 against what it must be worth at 18 to meet those costs, so anything payable after 18 is discounted back at the same 12%. Figures are illustrative mid-range estimates, not quotes or guarantees, and are shown before tax. How gains are taxed changes when your child turns 18 (see the FAQs below) and depends on the scheme, so confirm your own position with a tax adviser.
Your ₹5,000/mo builds

QR code. Scan it with your phone camera to open baby.money and install the app.Scan to install on your phone
Get it onApp Store Get it onGoogle Play

They started while it was only a thought.

“I started a SIP for my daughter the day she was born on baby.money. I’ll keep it running till she turns 18.”
Himanshu Ranjan SahuDad and project manager · baby.money customer

Built for parents who think way ahead

A separate account, just for them

Most parents invest for a child out of their own folio, where it mixes with everything else and is always one emergency away from being spent on something else. This is a separate mutual fund account in your child’s name, under your custody. Clearly separate. No mixing.

Gift money that keeps growing

When relatives gift money on birthdays or festivals, invest it in seconds, right from the app. One tap. Their love becomes your child’s legacy.

Tax, explained as you go

While your child is under 18, gains are taxed in your hands. From the month they turn 18, gains are taxed in theirs. Two separate accounts give you room to plan the redemption. We guide you at every tax touchpoint.

You don’t need to be a finance expert

baby.money makes it simple. One evening now; eighteen years of quiet work.

Active in minutes

Open your child’s account with their birth certificate and your own KYC.

The SIP runs itself

Set a SIP once. It runs on time, every time, till the child turns 18.

See where it could reach

See what your child’s fund could be worth at 18, 21 or 25.

A nudge when it matters

A reminder when your income grows, so the SIP can grow with it. No alerts telling you to act on a dip.

We do the choosing

Four children’s funds. Not two thousand.

All your children, one view

All your children’s accounts in one view. Switch between kids in a tap.

Let the whole family in

Stop spending their gift money.

Think about the envelopes this year. Every one of them came with a blessing and a number written inside, and you meant to do something sensible with all of it, you really did, but some went on a toy that has already lost a wheel and the rest just quietly became groceries and a phone bill, the way money does when nobody is watching it. None of it is still theirs.

It could have been compounding.

First birthdayDiwaliAnnaprasanFirst day of schoolRakhi“Just because”
🎂 Birthday gift to Aaravfrom Dadu
₹11,000
invested into Aarav’s fund · today
Could be worth ≈ ₹68,000 by 18 →
At 12% assumed p.a. Illustration, not a guarantee.

Change it whenever you need

Step it up. Pause it. Restart it.

Gifts and one-off top-ups

Cash gifted by grandparents or relatives? Invest it directly into your child’s account and let it compound.

Locked for five years, on purpose

Redemption opens once five years are complete. The lock is there to protect your child’s investments from the one thing that reliably breaks compounding, which is a bad week and a good reason.

Schemes from four of India’s largest fund houses

SBIHDFCICICI PrudentialAxis
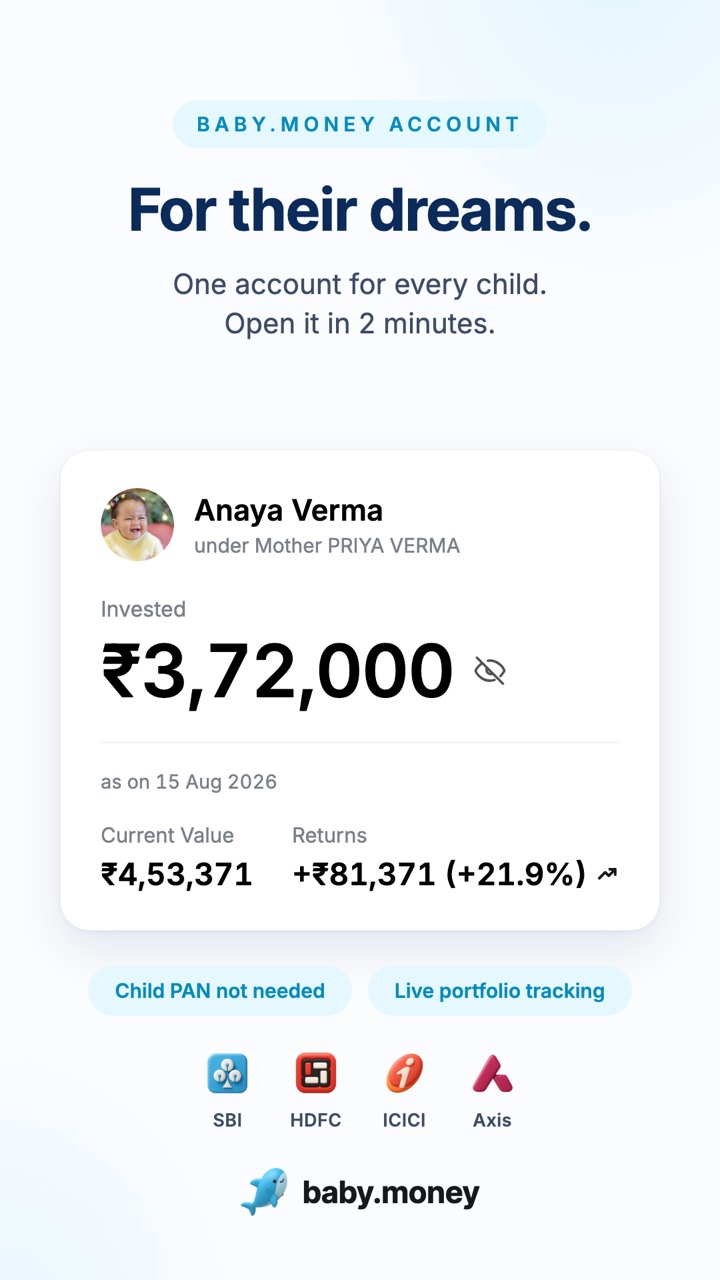
One account for every child: a child’s baby.money account card showing the amount invested, its current value and returns
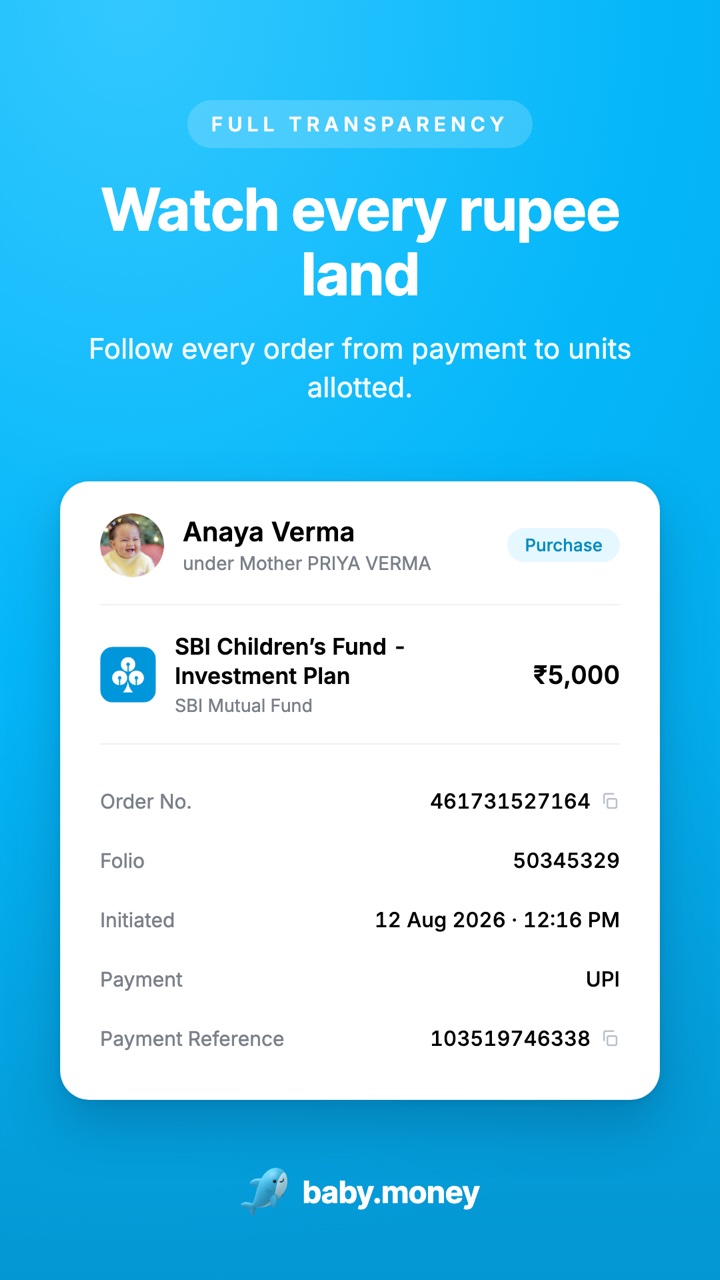
Full transparency: a purchase order into SBI Children’s Fund with its order number, folio and payment reference

Got questions? Here are the answers.

What does it mean to invest through a baby.money account?
When you invest for your child from your own account, the money is in your name, managed by you, and is technically part of your own wealth. Investing in your child’s name is structurally different: a separate mutual fund account is opened in your child’s name. You manage it entirely: you choose the funds, run the SIPs from your bank, and make every decision. The account belongs to your child. After they turn 18, we complete a one-time onboarding (including KYC) to activate their account and pass it on to them.
Who controls the account while my child is under 18?
You do, as the parent/guardian. The account is in your child’s name, but every decision sits with you: choosing funds, starting or stopping the SIP.
Which bank account funds the investments?
By default, when you open the child’s investment account with us, your bank account funds your child’s investments.
How do I withdraw money?
Redemption opens once the investment has completed five years. Until then the units stay locked, which is deliberate: it protects your child’s investments from being spent on something that felt urgent at the time. Once the lock is complete, withdrawals from your child’s account are credited to a bank account in your child’s name, which is also what lets you plan the tax once they turn 18. Redemption is also subject to scheme terms, exit load, cut-off times and applicable law.
How is it taxed?
While your child is under 18, capital gains are added to your income and taxed at your applicable slab for that fund type. From the month they turn 18, gains are taxed in your child’s income at their applicable slab.
Do I need my baby’s PAN to open the account?
No. Your child’s PAN is not required to open the account. Only your own PAN is mandatory.
Can only a parent open the account?
Either a parent (father or mother) or a court-appointed legal guardian can open and manage this account. If you’re a legal guardian, you’ll need the court order that names you as guardian.

Can’t find your answer? Email support@baby.money

Your child’s journey starts here

Three steps, one evening, and the compounding starts working for them.

1

Download

Get the app from the App Store or Google Play.

2

Add your child, confirm your KYC

Basic details for them, a quick KYC confirmation for you. Their PAN is never needed.

3

Start the SIP

Pick funds, set the mandate and amount, and you are done.

You won’t remember the ₹5,000. They’ll inherit the eighteen years.

Start the clock today.

The smallest, most boring thing you do this week could be the biggest thing you ever gave them. Set aside one quiet evening for it, the kind you look back on.

QR code. Scan it with your phone camera to open baby.money and install the app.Scan to install on your phone
Get it onApp Store Get it onGoogle Play

Download the baby.money app today.